

#051 Sensible Optimism: How We Think About Delivering Results
Thu, 15 Oct 2026 11:05:55 GMT
Cornerstone Ventures
Venture capital is, by nature, an optimistic business. We back founders before the market believes in them, write cheques before scaled revenues exist, and hold conviction through years of uncertainty. Without optimism, we could not last a week.
But optimism without discipline is just hope. And hope is not a strategy.
At Cornerstone, we have spent years developing what we call sensible optimism — a mindset that sits deliberately between blind faith and paralysing caution. It is the belief that great outcomes are achievable, paired with an honest understanding of what it actually takes to get there.
What sensible optimism is not
It is not the instinct to celebrate every milestone as a sign that everything will work out. It is not the reluctance to have hard conversations with founders when growth stalls, unit economics deteriorate, or the market moves in a direction the business was not built for. And it is certainly not the habit of averaging down on conviction when the underlying thesis has genuinely broken.
The venture ecosystem has seen what unchecked optimism looks like. The 2021 cycle produced companies valued at extraordinary multiples on the assumption that growth would compound indefinitely. When it did not, the correction was sharp, painful, and entirely predictable in hindsight. We at Cornerstone, moved with caution in those times — and we learned from it.
What sensible optimism actually means
It means we enter every investment with a clear view of what we can and cannot control. We cannot control interest rate cycles, global risk appetite, or the timing of public markets. We can control the quality of our entry valuations, the rigour of our due diligence, the depth of our founder relationships, the discipline with which we manage our portfolio through difficulty, and move with agility in these ever changing business realities.
It means we set expectations honestly — with our founders, our LPs, and ourselves. A portfolio company that is three years from a credible exit path does not benefit from being told otherwise. Founders deserve partners who engage with reality, not partners who validate narratives.
It means we back businesses with durable fundamentals — strong unit economics, defensible market positions, capital-efficient growth — because those are the businesses that survive the cycles we cannot predict.
And it means we stay invested in India’s long-term story without being blind to its near-term complexities. Currency pressure, regulatory shifts, and valuation corrections are real. So is the structural growth in enterprise software adoption, financial services penetration, and deep-tech innovation. We hold both of those truths simultaneously.
The venture ecosystem rewards those who remain constructive without becoming complacent.
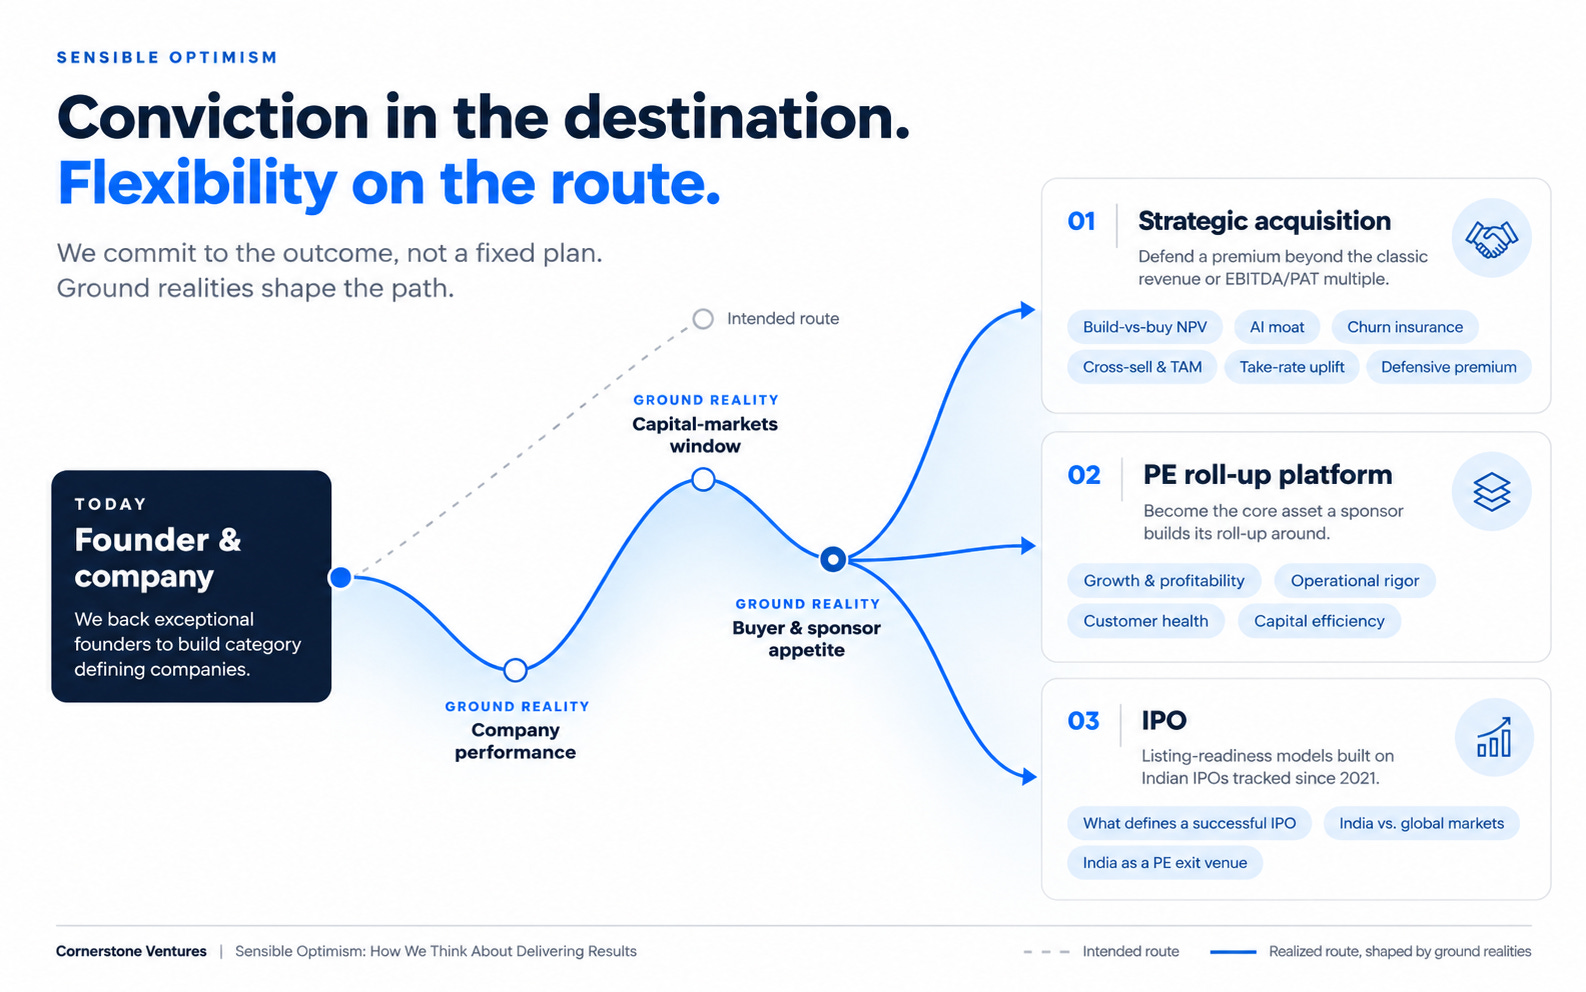
In practice, this means we follow an emergent strategy: guided by ground realities, we help our founders navigate toward the best available exit, whether a strategic acquisition, serving as the platform asset in a PE roll-up, or a public listing.
We bring a dedicated framework to each path. On IPOs, we have tracked the Indian public markets closely since 2021 and built models that quantify what distinguishes a successful listing, including where India converges with and diverges from other global markets. We have also tracked and analysed various sectors and the metrics at which the markets reward or penalise at listing. The framework thus arrived, is applied to our portfolio companies, enabling us to be on track to bag in the rewards at listing.
On PE roll-ups, we have worked alongside PE funds to understand the metrics that make the case for acquiring a platform asset, spanning growth and profitability, operational rigor, customer health, and capital efficiency. Most PE investments are operationally heavy businesses that are looking for catalysts to unlock growth. Our tech first portfolio companies become central pieces to a PE’s platform building approach.
On strategic acquisitions, we help founders defend a premium multiple by articulating the synergies an acquirer captures, over and above the classic revenue or EBITDA/PAT multiple. These include speed to market, framed as a build-versus-buy NPV that accounts for payroll, foregone fees, and reduced execution risk; an AI moat, capturing the option value of an agentic engine and its associated IP; churn insurance, through lower servicing costs or NRR uplift across the combined book; cross-sell revenue through the acquirer’s distribution; genuine TAM expansion via the acquirer’s relationships; take-rate improvement, through pricing-power normalization on the acquirer’s existing volume; and a defensive premium, reflecting the value of keeping the asset out of a competitor’s hands. One plus one is always more than two in these cases, delivering a much larger value for the buyer as combined forces.
Sensible optimism is not a compromise between two extremes — it is a distinct posture that allows us to act decisively when others hesitate, navigate the hold periods to ensure the exit paths remain unhindered and build trust with founders and LPs over time.
Outcomes in venture are never guaranteed. But the mindset with which you pursue them makes all the difference.
~ Deepak
Learn more about: Cornerstone Ventures | CGES Index
Disclaimer:
The data provided on this website (www.csvpfund.com) is for informational purpose only.
Any information provided on this website or any of the other digital assets owned & maintained by Cornerstone Venture Partners Fund, Mumbai, India (“CSVP”)and managed by the Investment Manager, Cornerstone Ventures Investment Advisers LLP, Mumbai India, does not constitute investment advice or investment recommendation nor does it constitute an offer to buy or sell or a solicitation of an offer to buy or sell shares or units in any of the investment funds or other financial instruments.
The Cornerstone Global Enterprise SaaS Index (“CGES Index”) ™ is a trademark of CSVP. The CGES Index is created & maintained using a proprietary algorithm and is to be used for informational purpose only. It is not to be construed as an investment advice or investment recommendation in any of the constituent companies / stocks that are directly or indirectly part of the Index. The Index is created using publicly available data published on the websites of the respective companies. All data presented is as per our internal research and analysis leveraging publicly available data and is being presented only for academic deliberation and discussion purposes and is not to be viewed as any specific commentary / recommendation / evaluation / conclusion on any of the companies / stocks that are directly or indirectly part of the CGES Index.
CSVP also analyses, maintains, and publishes certain financial and non-financial metrics (“SaaS Metrics”) on the Index at an aggregate level, and not at a specific company / stock level that constitute the CGES Index. These SaaS Metrics are provided purely for informational purpose and CSVP assumes no liability for accuracy, suitability, or completeness of the SaaS Metrics. The SaaS Metrics are created using publicly available third-party information and CSVP does not claim any ownership of the sourced data. CSVP is not responsible for the accuracy, suitability or completeness of the information originally disclosed by the owner of the information and any information provided herein. CSVP accepts no liability and offer no guarantee as to whether the information is up to date, correct or complete.
CSVP may have used third-party data, information, and content (including all text, data, graphics, and logos) on the website. CSVP assumes no ownership and intends no infringement of rights, titles, and claims (including copyright, brands, patents and other intellectual property or other rights) of the respective owners or authorized users of the respective content. Use of such content is from publicly available sources and for indicative and informational purpose only in good faith. All trademarks and registered trademarks are the properties of their respective owners. This website may contain references or links to other websites. References and links to third-party websites do not mean that CSVP adopts the content behind the reference or link as its own. When first setting up the link, CSVP will have checked the linked site for illicit content and found none at that time. However, CSVP have no influence over the current and future design or content of such linked sites and will accept no liability for such content or design. Any use of these websites is at your own risk. The obligation of CSVP to remove or block the use of information according to the general laws from the time of knowledge of a concrete violation of the law remains unaffected.

X
Contact Us
contact@csvpfund.comGet our latest updates on


Contact Us
contact@csvpfund.comGet our latest updates on
Contact Us
contact@cornerstoneventures.vcGet the latest updates on
Cornerstone Venture Partners Fund
9 Aug 2018
IN/AIF1/18-19/0572
Cornerstone Ventures Investment Fund
11 Dec 2023
IN/AIF2/23-24/1406
Contact Us
contact@csvpfund.comGet the latest updates on
Cornerstone Venture Partners Fund
9 Aug 2018
IN/AIF1/18-19/0572
Cornerstone Ventures Investment Fund
11 Dec 2023
IN/AIF2/23-24/1406
Copyright © 2025 Cornerstone.
All Rights Reserved.